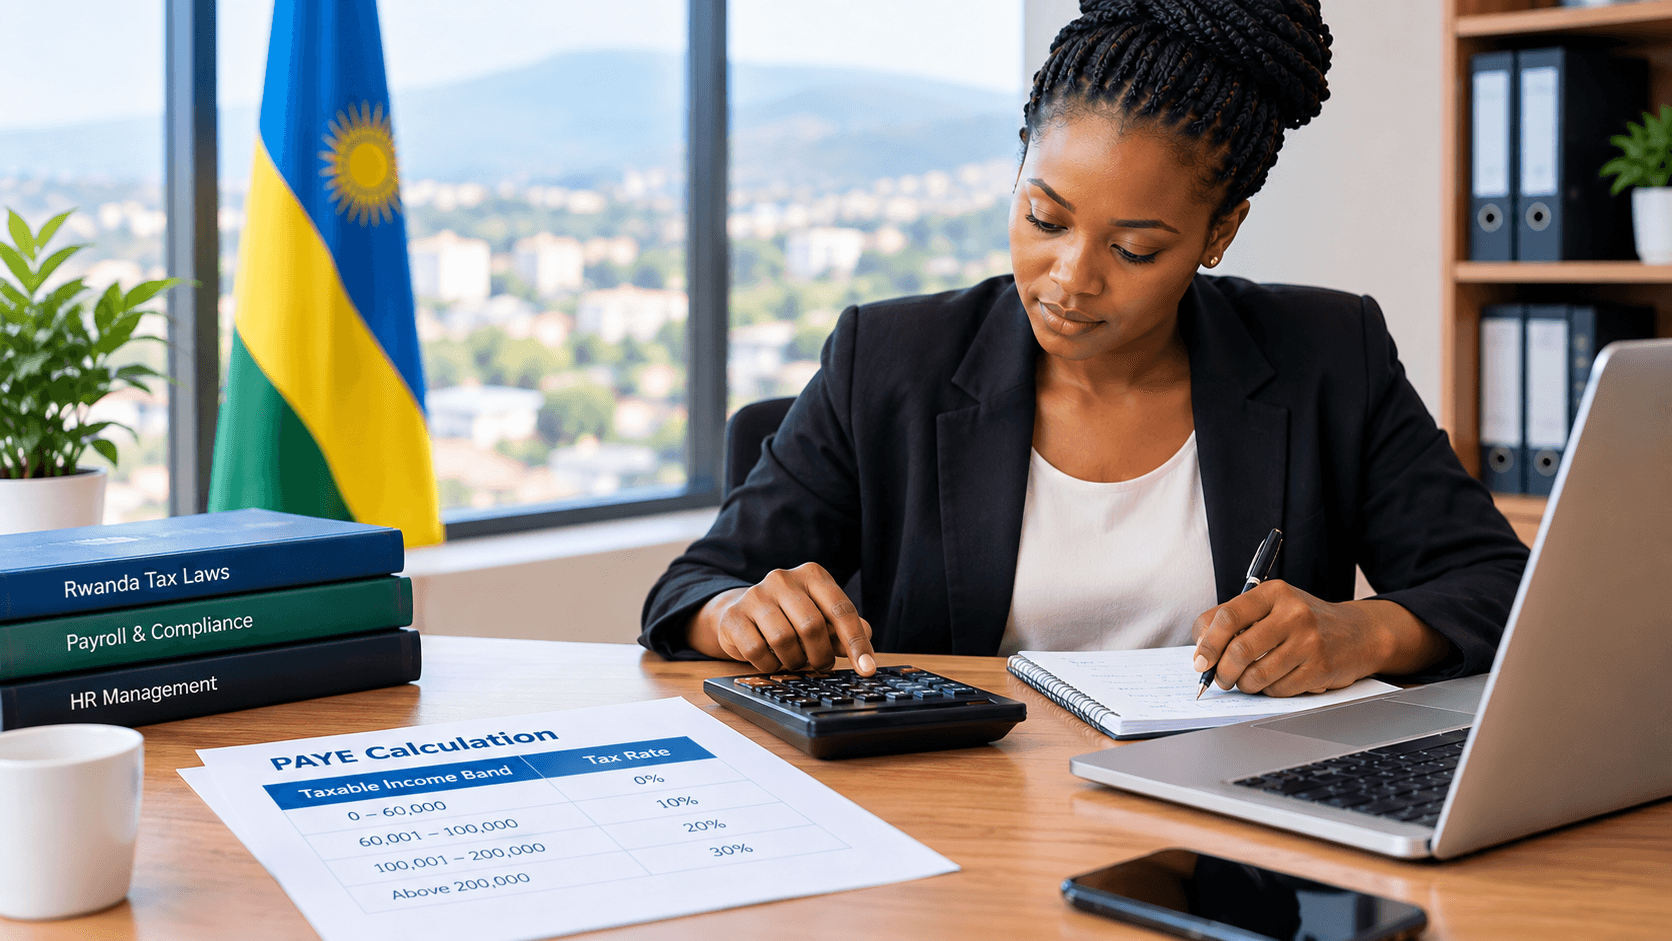
How to Calculate PAYE in Rwanda: A Practical Guide for Employers
Payroll is one of the most important financial responsibilities of any employer. Employees expect to receive their salaries accurately and on time, while employers must calculate the correct deductions, maintain proper records, and meet their tax obligations.
In Rwanda, one of the most important payroll deductions is Pay As You Earn (PAYE), the employment income tax withheld by an employer on behalf of an employee and remitted to the Rwanda Revenue Authority (RRA).
However, calculating PAYE is not always as simple as multiplying an employee's salary by a single tax rate. The calculation depends on the employee's taxable employment income and employment category. Permanent employees, casual labourers, and employees receiving income from more than one employer are subject to different rules.
This guide explains how PAYE works in Rwanda, how to calculate it step by step, and what employers should consider when processing payroll.
1. What is PAYE?
PAYE stands for Pay As You Earn. It is the system through which income tax on employment earnings is withheld at the point of payment.
Employers are generally responsible for calculating the tax, withholding it from employees' taxable earnings, declaring it, and paying it to the RRA within the prescribed deadline.
PAYE applies to more than basic monthly salaries. Depending on the nature of the payment, taxable employment income can include:
Basic salary and wages.
Overtime payments.
Bonuses and commissions.
Leave pay and sick pay.
Housing, transport, subsistence, and other taxable allowances.
Certain benefits provided to employees in cash or in kind.
Other payments made in respect of employment.
Certain payments are exempt from employment income tax under the applicable law. For example, qualifying employer contributions to the public social security institution and qualifying reimbursements of business expenses may be excluded.
Employers should therefore determine the taxable value of an employee's remuneration before applying the relevant PAYE rates.
2. PAYE rates for permanent employees in Rwanda
For ordinary employment income, Rwanda uses a progressive tax system. This means that different portions of taxable monthly income are taxed at different rates.
The applicable monthly tax bands are:
| Monthly taxable income | Tax rate |
|---|---|
| FRW 0 to FRW 60,000 | 0% |
| Above FRW 60,000 to FRW 100,000 | 10% |
| Above FRW 100,000 to FRW 200,000 | 20% |
| Above FRW 200,000 | 30% |
These rates apply to the relevant portion of income within each band, not to the employee's entire salary.
For example, an employee earning FRW 250,000 per month does not pay 30% on the whole FRW 250,000. The first FRW 60,000 is taxed at 0%, the next FRW 40,000 at 10%, the next FRW 100,000 at 20%, and only the remaining FRW 50,000 at 30%.
Understanding this distinction is essential for accurate payroll processing.
3. How to calculate PAYE for a permanent employee
Consider an employee earning a monthly taxable salary of FRW 250,000.
The calculation is as follows:
| Income portion | Calculation | Tax due |
|---|---|---|
| First FRW 60,000 | 60,000 × 0% | FRW 0 |
| Next FRW 40,000 | 40,000 × 10% | FRW 4,000 |
| Next FRW 100,000 | 100,000 × 20% | FRW 20,000 |
| Remaining FRW 50,000 | 50,000 × 30% | FRW 15,000 |
| Total PAYE | FRW 39,000 |
The employee's monthly PAYE is FRW 39,000.
The same calculation can be expressed using a simplified formula for ordinary monthly taxable employment income:
For taxable income up to FRW 60,000, PAYE is zero.
For income above FRW 60,000 and up to FRW 100,000, PAYE is 10% of the amount above FRW 60,000.
For income above FRW 100,000 and up to FRW 200,000, PAYE is FRW 4,000 plus 20% of the amount above FRW 100,000.
For income above FRW 200,000, PAYE is FRW 24,000 plus 30% of the amount above FRW 200,000.
For an employee earning FRW 500,000 in monthly taxable income, the calculation is:
PAYE = FRW 24,000 + (FRW 300,000 × 30%)
PAYE = FRW 114,000.
Using these formulas makes it easier for finance teams to verify payroll calculations and identify errors.
4. How to calculate PAYE for casual labourers
Casual labourers are subject to a different PAYE treatment.
Under the RRA's guidance, a casual labourer is an employee performing unskilled work, without machinery or equipment requiring special skills, who is engaged by an employer for no longer than 30 days during a tax period.
The classification depends on the legal criteria, not simply on whether an employer pays someone daily or calls them a temporary worker.
The PAYE calculation for a qualifying casual labourer is:
| Monthly taxable income | Tax treatment |
|---|---|
| First FRW 60,000 | 0% |
| Amount above FRW 60,000 | 15% |
Example: Casual labourer earning FRW 100,000
Assume a qualifying casual labourer receives taxable employment income of FRW 100,000.
The first FRW 60,000 is taxed at 0%.
The remaining FRW 40,000 is taxed at 15%.
PAYE = FRW 60,000 × 0% + FRW 40,000 × 15%
PAYE = FRW 6,000.
The employer should not automatically apply the ordinary progressive PAYE bands to a worker who qualifies for the casual labourer treatment.
It is equally important not to classify every temporary, daily-paid, or short-term worker as a casual labourer. Where the legal criteria are not met, the appropriate employment income tax treatment must be determined under the applicable rules.
5. How to calculate PAYE for employees with more than one employer
Employees who receive employment income from multiple employers are subject to specific withholding rules.
The employer paying the employee's principal employment income is treated as the first employer. That employer applies the ordinary PAYE rules where applicable.
An additional employer must withhold PAYE at the flat rate of 30% on the taxable employment income it pays.
Example: Employee with two employers
Suppose an employee receives:
FRW 300,000 per month from the first employer.
FRW 150,000 per month from a second employer.
The first employer calculates PAYE using the progressive tax bands.
PAYE from the first employer:
FRW 24,000 + (FRW 100,000 × 30%) = FRW 54,000.
The second employer applies the 30% withholding rate:
FRW 150,000 × 30% = FRW 45,000.
The respective employers withhold FRW 54,000 and FRW 45,000.
The employee must inform the employers which one is the first employer, and the employer should confirm that status as required. Employees receiving income from multiple employers may have additional annual declaration or refund considerations under the applicable rules.
For employers, the lesson is straightforward: payroll onboarding should capture whether an employee has another employer and whether the company is the employee's first employer for PAYE purposes.
6. What happens when an employee receives allowances or benefits?
A common payroll mistake is calculating PAYE using basic salary alone.
Taxable employment income can include allowances and certain benefits in kind. If these are omitted, the employer may understate taxable income and withhold insufficient tax.
For example, suppose an employee receives:
Basic salary: FRW 300,000.
Taxable transport allowance: FRW 30,000.
Taxable housing allowance: FRW 50,000.
Assuming all three amounts are taxable and no other adjustments apply, monthly taxable employment income is FRW 380,000.
The ordinary PAYE calculation is:
FRW 24,000 + (FRW 180,000 × 30%) = FRW 78,000.
The calculation is based on FRW 380,000, not the basic salary of FRW 300,000.
Benefits in kind can require additional valuation rules. For example, the tax law provides specific valuation methods for employer-provided accommodation and motor vehicles. Employers should use the applicable statutory valuation rather than automatically treating every benefit as equal to its cash cost.
7. PAYE is only one part of payroll
Calculating PAYE correctly is essential, but it does not complete the payroll process.
Depending on the employee and the applicable rules, payroll may also involve:
Pension and social security contributions.
Other applicable statutory deductions.
Approved employee-specific deductions.
Calculation of net salary.
Preparation of payslips and payroll reports.
Declaration and remittance of the amounts due to the relevant authorities.
These items should be calculated according to their own legal rules. Employers should not assume that every deduction is calculated on the same earnings base or that every deduction is applied before PAYE.
For that reason, a reliable payroll process separates the calculation of taxable employment income, PAYE, other statutory contributions, and net pay.
8. When must employers declare and pay PAYE?
According to the Rwanda Revenue Authority, employers required to withhold PAYE must declare and pay the tax within 15 days following the end of the month for which the tax is due.
Employers must also maintain proper payroll and accounting records to support the amounts withheld, declared, and paid.
Accurate employee records, clear payroll calculations, and a consistent monthly closing process help reduce errors and make it easier to demonstrate compliance when records are reviewed.
Employers should confirm their applicable filing frequency and obligations with the RRA, particularly where special circumstances apply.
9. Common PAYE calculation mistakes
The following mistakes can lead to inaccurate payroll results:
Applying one tax rate to the entire salary. Progressive PAYE rates apply to the relevant portions of taxable income. The highest rate does not automatically apply to the entire salary.
Using basic salary as the only taxable amount. Taxable allowances, bonuses, and benefits may need to be included.
Applying the wrong employee category. Casual labourers and employees with additional employers have specific withholding rules.
Confusing PAYE with other statutory deductions. Pension contributions and other deductions must be handled according to their own applicable rules.
Failing to keep supporting records. Employers need to be able to explain how taxable income and tax due were calculated.
Missing filing deadlines. Even a correctly calculated amount can create compliance problems if it is declared or paid late.
10. Making payroll more accurate with KaziSync
As an organization grows, payroll becomes more complex. HR teams may need to reconcile attendance records, employee schedules, allowances, salary changes, leave, and other adjustments before calculating each employee's pay.
Managing these activities through disconnected spreadsheets can make it harder to identify errors, maintain consistent records, and reproduce calculations when questions arise.
KaziSync brings attendance, payroll, payslips, leave management, and other workforce processes together in one system. For employers managing multiple departments, branches, or large teams, this integrated approach can help organize payroll information and reduce reliance on manual processes.
Payroll software should support accurate calculations, transparent records, and a repeatable process. Employers remain responsible for ensuring that the applicable tax rules and employee classifications are correctly reflected in their payroll configuration.
Conclusion
Calculating PAYE in Rwanda starts with identifying taxable employment income and determining the correct employee category. Ordinary employment income uses progressive monthly tax bands, qualifying casual labourers have a separate calculation, and additional employers must apply the applicable 30% withholding rule.
Employers who understand these distinctions are better positioned to process payroll accurately, maintain reliable records, and meet their tax obligations.
As payroll and workforce operations become more complex, having a structured and dependable process becomes increasingly important.
Learn how KaziSync helps employers manage attendance, payroll, payslips, and workforce operations in one platform. Visit KaziSync to learn more.
Official reference
For the current rules and additional guidance, consult the Rwanda Revenue Authority's PAYE guidance and its PAYE registration and employer obligations guidance.
Disclaimer: This article is for general educational purposes and is not a substitute for professional tax advice. Employers should verify the applicable law and current RRA guidance before processing payroll.